Weekly Market Report
Executive Summary
The week delivered a stark bifurcation: mega-cap incumbents held the line while AI infrastructure names were decisively re-rated lower. With AAPL the sole gainer among leaders (+2.0%) and the entire laggard cohort — CRWV, SMCI, DELL, AMAT, ANET — down 18-25%, the tape signals a sharp unwind in the "picks-and-shovels" AI build-out trade rather than broad risk-off. The implication: investors are reassessing the durability of AI capex monetization timelines, not the AI thesis itself.
Market Dynamics
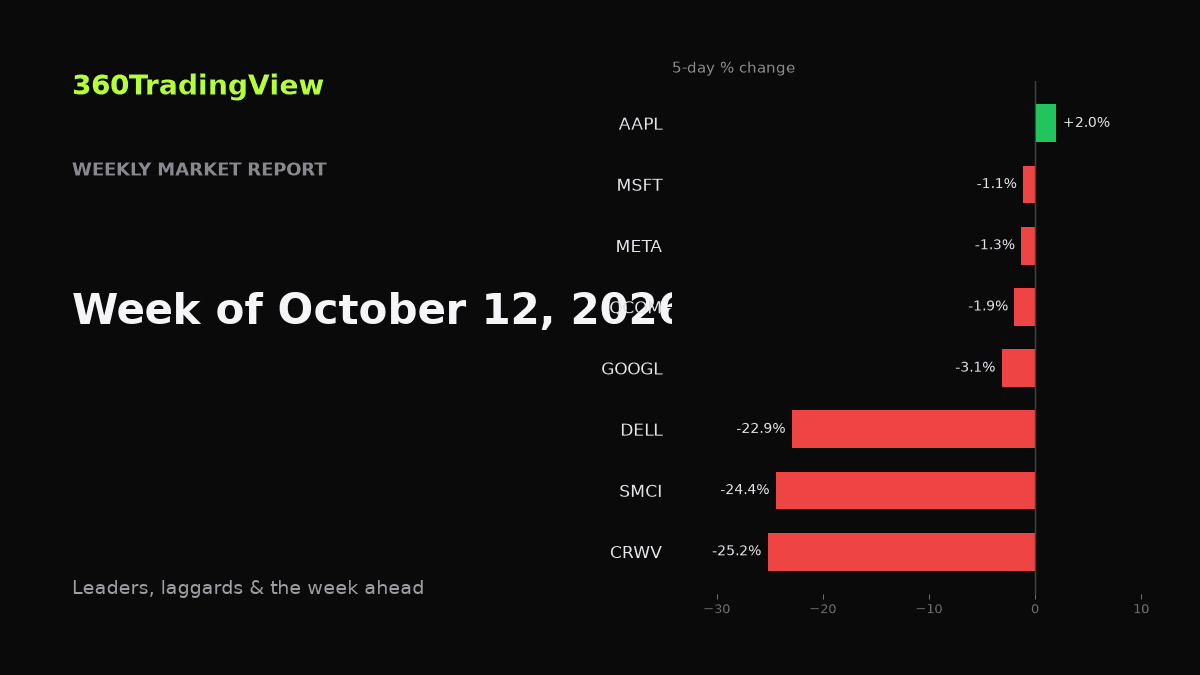
Leadership was defensive-mega-cap in character. AAPL (+2.0%) stood alone on the plus side, while the rest of the top-five "leaders" were actually modest decliners — MSFT (-1.1%), META (-1.3%), QCOM (-1.9%), GOOGL (-3.1%) — meaning the week's "winners" largely won by losing less. That pattern typically reflects rotation into perceived earnings durability and balance-sheet quality rather than fresh risk appetite.
The damage was concentrated and thematic. Every top laggard sits along the AI hardware stack: CRWV (-25.2%) in GPU cloud, SMCI (-24.4%) and DELL (-22.9%) in AI servers, AMAT (-19.3%) in semi cap-ex, and ANET (-18.3%) in AI networking. Declines of this magnitude, clustered this tightly along a single value chain, point to a factor move — a re-rating of AI infrastructure multiples — rather than idiosyncratic news.
Exhibit 1 — Weekly performance, selected names (5-day % change)
| Ticker | 5-Day | Read |
|---|---|---|
| AAPL | +2.0% | Leader |
| MSFT | -1.1% | Leader |
| META | -1.3% | Leader |
| QCOM | -1.9% | Leader |
| GOOGL | -3.1% | Leader |
| CRWV | -25.2% | Laggard |
| SMCI | -24.4% | Laggard |
| DELL | -22.9% | Laggard |
| AMAT | -19.3% | Laggard |
| ANET | -18.3% | Laggard |
Sector Read-Through
AI infrastructure under pressure. The simultaneous drawdown across GPU hosting (CRWV), server OEMs (SMCI, DELL), semi equipment (AMAT), and networking (ANET) suggests the market is stress-testing capex absorption and margin assumptions across the full build-out chain. When the entire stack moves together by ~20%, the signal is typically about demand visibility and pricing power, not any single vendor's execution.
Mega-cap resilience, not strength. AAPL's modest gain alongside shallow declines in MSFT, META, and GOOGL points to a flight toward cash-generative platforms where AI is an input, not the product. Hyperscaler-adjacent GOOGL's -3.1% is notable: it was the softest of the mega-caps, hinting that even platform owners aren't immune when capex narratives are challenged.
Semis bifurcating. QCOM's shallow -1.9% versus AMAT's -19.3% underscores a growing split between semi end-markets (handset/edge) and the AI capex complex. The read-through: not all "semis" are trading as one trade anymore.
The Week Ahead
Market participants will likely be watching whether the AI infrastructure drawdown stabilizes or extends into adjacent names not yet marked down. Key framing questions for the days ahead:
- Breadth of the unwind: Does weakness stay confined to the hardware stack, or begin bleeding into hyperscalers and foundational semis?
- Mega-cap leadership test: Can AAPL-style outperformance broaden, or does it narrow further?
- Dispersion signal: A ~27-point spread between the best and worst names this week is unusually wide; monitor whether that compresses (mean reversion) or persists (regime shift).
Educationally, drawdowns of 20%+ in a single week often invite tactical interest, but historically the first bounce in a factor unwind is not always the durable one. Position sizing and time horizon matter more than entry timing in these conditions.
Key Takeaways
- AI infrastructure was repriced, not the AI thesis — the pain was concentrated along a single value chain.
- Mega-cap "leadership" was defensive — AAPL aside, the leaders simply fell less.
- Dispersion widened materially — a ~27-point gap between top gainer and top laggard signals factor stress.
- Semis are no longer one trade — QCOM vs. AMAT illustrates the growing split between edge and AI capex.
- Watch for contagion vs. containment — whether hyperscalers hold will define the next leg.
Educational only. Not financial advice.