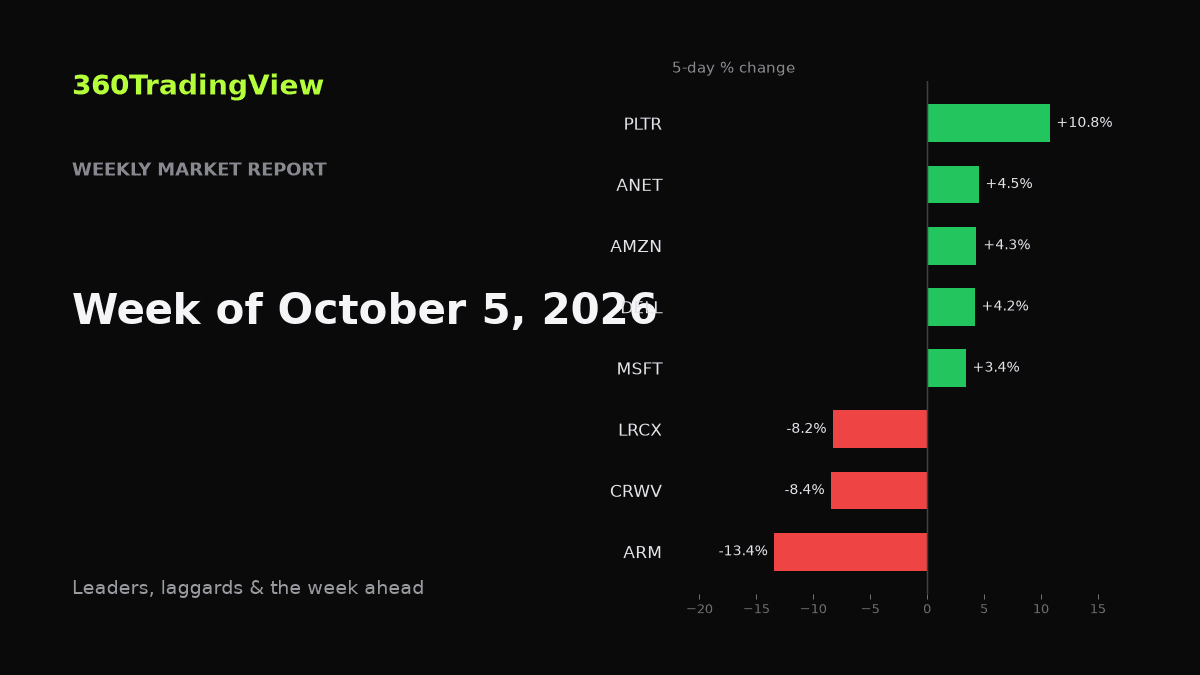
Weekly Market Report
Executive Summary
This week's tape revealed a sharp bifurcation within the AI complex: software, hyperscaler platforms, and AI-adjacent networking led, while semiconductor capital equipment and licensing names were sold hard. The rotation suggests investors are re-pricing where AI value is accruing — favoring deployment and consumption layers over upstream silicon fabrication and IP. For portfolios anchored to the "picks-and-shovels" thesis, this week was a reminder that leadership within a secular theme is rarely static.
Market Dynamics
Leadership this week clustered around AI application and infrastructure monetization. Palantir (+10.8%) led decisively, extending the premium being placed on enterprise AI software with visible revenue traction. Arista Networks (+4.5%) and Dell (+4.2%) reinforced the datacenter-build narrative on the networking and systems-integration side, while mega-cap platforms Amazon (+4.3%) and Microsoft (+3.4%) rounded out the leaders — a signal that capital continues to concentrate in balance-sheet-rich hyperscalers with direct AI distribution.
The laggard list tells the inverse story. ARM (-13.4%) was the week's standout decliner, with CoreWeave (-8.4%), Lam Research (-8.2%), Applied Materials (-6.1%), and Qualcomm (-5.1%) all under meaningful pressure. The common thread: semiconductor capital equipment, foundry-adjacent licensing, and AI compute pure-plays — the parts of the stack most sensitive to capex cadence, order timing, and valuation compression when rate expectations shift.
Exhibit 1 — Weekly performance, selected names (5-day % change)
| Ticker | 5-Day | Read |
|---|---|---|
| PLTR | +10.8% | Leader |
| ANET | +4.5% | Leader |
| AMZN | +4.3% | Leader |
| DELL | +4.2% | Leader |
| MSFT | +3.4% | Leader |
| ARM | -13.4% | Laggard |
| CRWV | -8.4% | Laggard |
| LRCX | -8.2% | Laggard |
| AMAT | -6.1% | Laggard |
| QCOM | -5.1% | Laggard |
The spread between the top gainer (+10.8%) and worst laggard (-13.4%) exceeded 24 percentage points in a single week — a dispersion level that typically reflects factor rotation rather than broad directional conviction.
Sector Read-Through
AI software and platforms held the bid. The strength in PLTR alongside MSFT and AMZN points to continued investor preference for names where AI translates into recognizable enterprise revenue or cloud consumption — not just capex intention.
Networking and systems benefited; wafer-fab equipment did not. ANET and DELL rising while LRCX and AMAT fell more than 6% each suggests the market is distinguishing between shipping-today AI infrastructure and building-tomorrow fab capacity. This is a meaningful nuance: it implies some concern about the slope and timing of the next semi-cap order cycle.
Compute pure-plays and IP licensors underperformed. ARM's -13.4% and CRWV's -8.4% are the sharpest signals in the dataset. Both names carry rich multiples tied to forward AI narratives, making them most exposed to any re-rating of growth assumptions or risk appetite.
The Week Ahead
Investors monitoring the current rotation may want to watch several educational reference points:
- Semi-cap commentary and order trends — further weakness in LRCX/AMAT would reinforce a capex-digestion narrative; stabilization would suggest this week was positioning, not fundamental.
- Hyperscaler cloud spend disclosures — directly relevant to the sustainability of the MSFT/AMZN leadership.
- Rate-sensitive growth behavior — ARM and CRWV are useful tells for duration appetite within tech.
- Networking order flow (ANET-type names) — a leading indicator for whether AI buildout momentum is broadening or narrowing.
None of these are directional calls; they are observation points to help frame whether this week's rotation extends or reverses.
Key Takeaways
- Leadership rotated from upstream silicon to AI software and hyperscalers — a shift worth tracking, not extrapolating.
- Semi-cap equipment weakness (LRCX, AMAT) warrants attention as a potential early signal on capex cadence.
- ARM's -13.4% move highlights multiple compression risk in high-expectation AI names.
- Mega-cap platforms remain a defensive expression of the AI thesis when dispersion rises.
- Intra-theme dispersion >24 points suggests selectivity, not thematic exit — a stock-picker's tape.
Educational only. Not financial advice.