360TradingView Weekly Market Report
Executive Summary
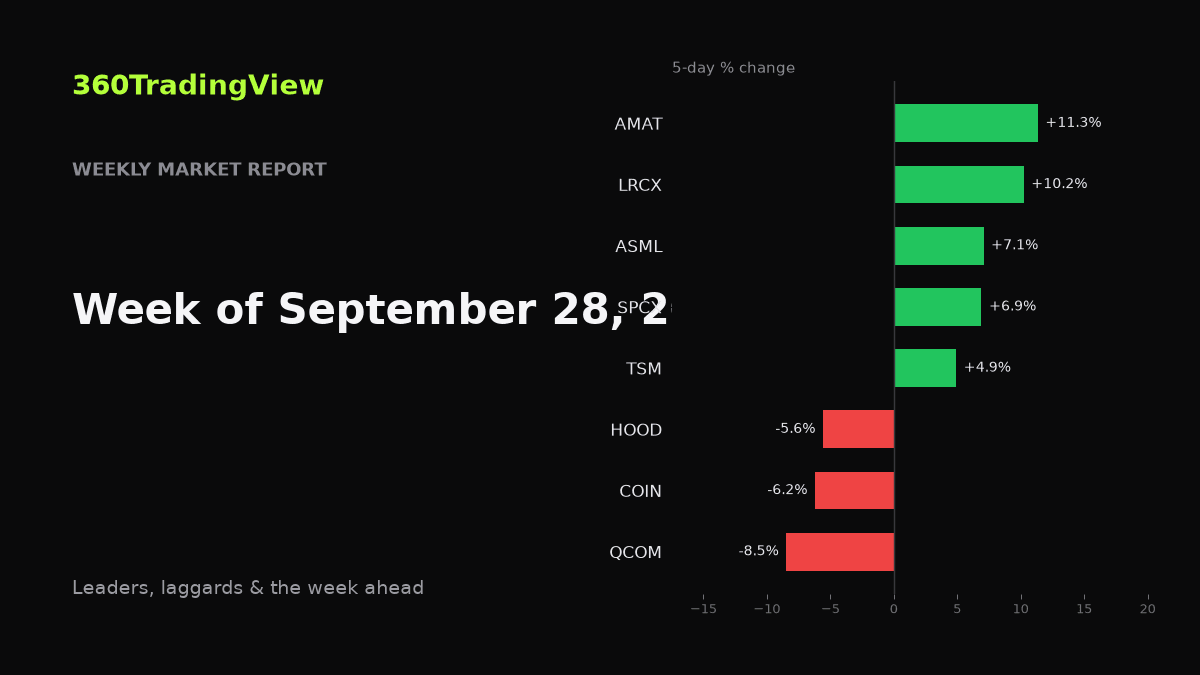
Semiconductor capital equipment decisively led markets this week, with AMAT (+11.3%) and LRCX (+10.2%) posting double-digit gains alongside ASML (+7.1%) and TSM (+4.9%). The pattern points to renewed conviction in the AI infrastructure capex cycle — specifically the "picks-and-shovels" layer — even as fintech, crypto-adjacent names, and parts of mega-cap tech lagged. The dispersion suggests capital is rotating within tech rather than away from it, favoring hardware enablers over consumer-facing platforms and rate-sensitive financials.
Market Dynamics
The week's defining theme was the concentration of strength in wafer fab equipment (WFE) and foundry exposure. AMAT, LRCX, and ASML — the three pillars of the global semi-cap complex — moved together with gains between +7% and +11%, a correlation signature that typically reflects a repricing of forward capex expectations rather than idiosyncratic news. TSM's +4.9% move completes the vertical: equipment, lithography, and foundry all bid.
In contrast, QCOM's -8.5% decline stands out as a notable divergence within semis, suggesting the market is distinguishing between AI infrastructure beneficiaries and handset-exposed franchises. META's -3.1% softness hints that mega-cap platform leadership is narrowing, while COIN (-6.2%), HOOD (-5.6%), and SOFI (-4.9%) point to pressure on rate-sensitive and crypto-adjacent fintech — a cohort that typically underperforms when risk appetite narrows or yield expectations shift.
Exhibit 1 — Weekly performance, selected names (5-day % change)
| Ticker | 5-Day | Read |
|---|---|---|
| AMAT | +11.3% | Leader |
| LRCX | +10.2% | Leader |
| ASML | +7.1% | Leader |
| SPCX | +6.9% | Leader |
| TSM | +4.9% | Leader |
| QCOM | -8.5% | Laggard |
| COIN | -6.2% | Laggard |
| HOOD | -5.6% | Laggard |
| SOFI | -4.9% | Laggard |
| META | -3.1% | Laggard |
Sector Read-Through
AI infrastructure capex is being re-rated — selectively. The symmetry across AMAT, LRCX, and ASML implies the move is about the WFE cycle itself, not a single catalyst. When equipment and foundry rally together, the market is typically pricing in a longer or steeper capex curve from hyperscaler and foundry customers.
Semis are no longer a monolith. QCOM's -8.5% drop against double-digit gains in equipment names highlights an increasingly bifurcated semiconductor tape. Exposure to AI training/inference infrastructure is being rewarded; exposure to mature end-markets like smartphones is not. Investors treating "semis" as a single factor may be mismeasuring risk.
Fintech and crypto-adjacent names are under pressure as a cohort. COIN, HOOD, and SOFI all declining 4.9–6.2% in the same week — alongside relative weakness in META — suggests risk capital is rotating out of consumer-facing, high-beta pockets and into hardware enablers of enterprise AI spend.
The Week Ahead
Market participants may want to monitor several educational reference points:
- Follow-through in WFE names. Whether AMAT, LRCX, and ASML can hold gains will indicate if this week's move reflects a durable re-rating or a short-cycle positioning shift.
- QCOM's divergence. Watch for signs the weakness is contained to handset-exposed semis versus bleeding into the broader complex.
- Fintech cohort behavior. COIN, HOOD, and SOFI tend to move with risk appetite and rate expectations; stabilization or continued softness will be informative on broader sentiment.
- META and mega-cap breadth. A single mega-cap underperforming is noise; sustained divergence from the group would warrant attention to leadership composition.
None of these observations constitutes a forecast. They are reference points for framing incoming data.
Key Takeaways
- The AI capex trade is maturing from GPUs toward the equipment layer — WFE's symmetric move is the week's clearest signal.
- "Semis" is now a dispersion story, not a single factor; QCOM's -8.5% against AMAT's +11.3% underscores the gap.
- Fintech and crypto-adjacent names moved as a cohort lower, consistent with narrowing risk appetite in high-beta pockets.
- Mega-cap leadership is thinning at the margin, as suggested by META's -3.1% relative softness.
- Rotation within tech, not away from it — the week's pattern favors enterprise AI enablers over consumer-facing platforms.
Educational only. Not financial advice.