360TradingView Weekly Market Report
Executive Summary
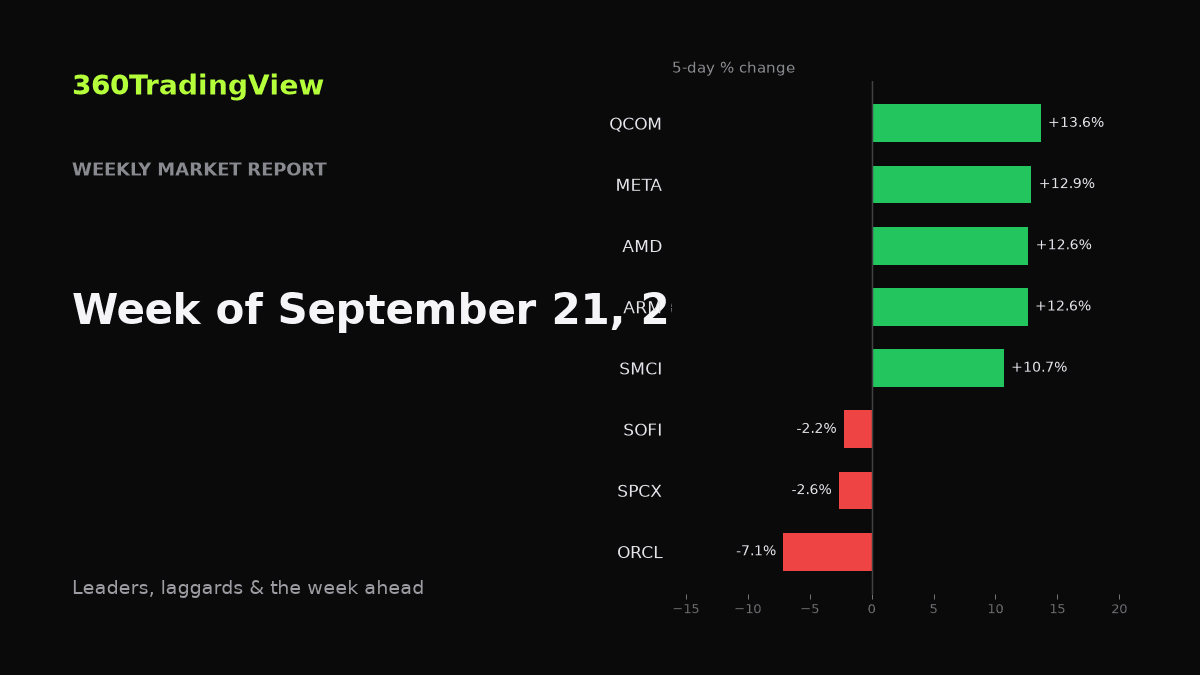
Semiconductors and AI hardware decisively led the tape this week, with QCOM (+13.6%), AMD (+12.6%), ARM (+12.6%), and SMCI (+10.7%) posting double-digit gains alongside META (+12.9%). The dispersion is notable: while chip and edge-AI names ripped, ORCL fell -7.1% and hyperscaler-adjacent mega-caps GOOGL (-1.6%) and AMZN (-1.6%) drifted lower — suggesting capital is rotating within the AI complex rather than flowing into it uniformly.
Market Dynamics
Leadership this week was concentrated in the compute and silicon layer of the AI stack. Four of the top five gainers were semiconductor names spanning mobile (QCOM), accelerators (AMD), IP/design (ARM), and AI systems (SMCI). META's outsized move stands apart from the mega-cap cohort, breaking from the softness in GOOGL and AMZN and reinforcing a bifurcation within Big Tech.
The laggard list tells the more interesting story. ORCL's -7.1% drawdown was the week's most pronounced single-name reversal among major tech, while other cloud- and platform-oriented names underperformed the broader semi rally. That pattern is consistent with investors reassessing the economics of AI infrastructure spend — favoring the sellers of picks-and-shovels over the buyers.
Exhibit 1 — Weekly performance, selected names (5-day % change)
| Ticker | 5-Day | Read |
|---|---|---|
| QCOM | +13.6% | Leader |
| META | +12.9% | Leader |
| AMD | +12.6% | Leader |
| ARM | +12.6% | Leader |
| SMCI | +10.7% | Leader |
| ORCL | -7.1% | Laggard |
| SPCX | -2.6% | Laggard |
| SOFI | -2.2% | Laggard |
| GOOGL | -1.6% | Laggard |
| AMZN | -1.6% | Laggard |
Sector Read-Through
Semis & AI hardware — clear leadership. The synchronized moves in QCOM, AMD, ARM, and SMCI point to broad-based demand for AI compute exposure, not a single-name catalyst. Breadth across mobile, merchant accelerators, and systems integrators suggests a factor bid rather than idiosyncratic news flow.
Mega-cap divergence. META's +12.9% versus GOOGL -1.6% and AMZN -1.6% is the week's cleanest divergence. The "Magnificent" cohort is no longer trading as a monolith; positioning appears to be re-differentiating around ad monetization, capex intensity, and AI ROI narratives.
AI infrastructure buyers under pressure. ORCL's -7.1% is the standout. When the silicon suppliers rally hard while a large enterprise-cloud buyer sells off, the market is often signaling concern about margin absorption of AI capex — a dynamic worth monitoring across other hyperscaler-linked names. SOFI's -2.2% and SPCX's -2.6% suggest the risk-on tone did not extend to more speculative fintech and thematic vehicles.
The Week Ahead
Investors may find it useful to track whether this week's semiconductor leadership broadens or narrows. A widening of participation beyond the top gainers would support a durable rotation thesis; a narrowing back toward a handful of names would suggest positioning-driven froth.
Key items to watch as educational reference points:
- Follow-through in QCOM, AMD, ARM, SMCI — do this week's gains hold, or do they retrace? Sustained strength versus quick give-back changes the read materially.
- ORCL stabilization — whether the -7.1% marks a discrete repricing or the start of a longer reassessment of AI-buyer economics.
- META vs. GOOGL/AMZN spread — continued divergence would reinforce the mega-cap differentiation theme.
- Breadth of the AI trade — watch whether laggard mega-caps recouple with semis or continue to lag.
Key Takeaways
- AI leadership is now silicon-led, with four semi names (QCOM, AMD, ARM, SMCI) all up double digits.
- Big Tech is no longer a monolith: META (+12.9%) sharply diverged from GOOGL and AMZN (both -1.6%).
- ORCL's -7.1% is the tell — the market may be repricing the economics of AI infrastructure buyers versus sellers.
- Risk appetite was selective, not broad: speculative names (SPCX -2.6%, SOFI -2.2%) did not participate in the semi rally.
- Watch breadth next week — the durability of this rotation depends on whether leadership widens beyond a handful of names.
Educational only. Not financial advice.