Weekly Market Report
Executive Summary
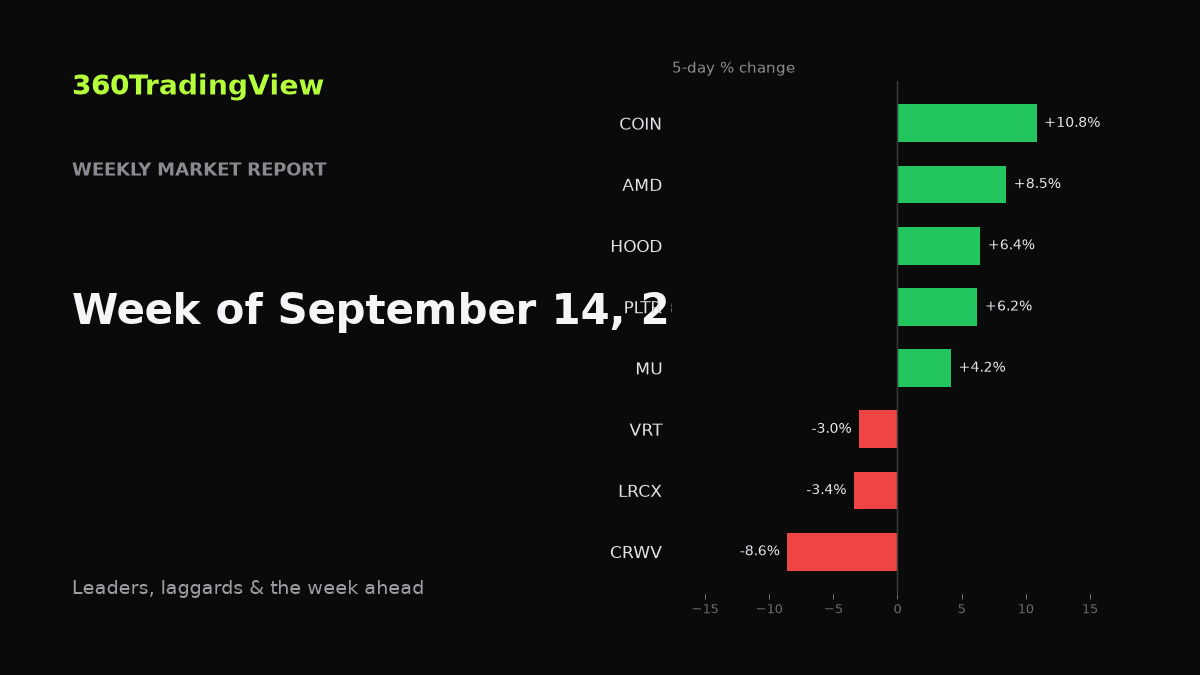
This week's tape revealed a sharp bifurcation within the AI and high-beta complex rather than a broad risk-on or risk-off move. Crypto-linked names and select semiconductor leaders (COIN +10.8%, AMD +8.5%, HOOD +6.4%) outpaced the field, while AI infrastructure and semi-cap equipment names lagged (CRWV -8.6%, LRCX -3.4%, VRT -3.0%, AMAT -2.6%). The dominant theme: capital rotated within the AI trade — favoring compute silicon and financial-rails beneficiaries, while trimming the picks-and-shovels build-out layer.
Market Dynamics
Leadership skewed toward names with direct exposure to end-demand monetization. AMD's +8.5% and MU's +4.2% suggest continued conviction in the compute and memory layer of the AI stack. Crypto-adjacent financials — COIN +10.8% and HOOD +6.4% — extended their run, consistent with risk appetite in digital assets and retail trading flow. PLTR's +6.2% reinforced the software-monetization narrative.
The lagging cohort tells the more interesting story. CRWV -8.6%, VRT -3.0%, and SMCI -2.5% cluster around the AI infrastructure build theme — neocloud, power/thermal, and server integration. Semi-cap equipment (LRCX -3.4%, AMAT -2.6%) softened alongside them, hinting at some rethink of capex pacing and forward wafer-fab equipment orders. This is not a repudiation of AI; it is a re-weighting away from the most capex-intensive expressions of it.
Exhibit 1 — Weekly performance, selected names (5-day % change)
| Ticker | 5-Day | Read |
|---|---|---|
| COIN | +10.8% | Leader |
| AMD | +8.5% | Leader |
| HOOD | +6.4% | Leader |
| PLTR | +6.2% | Leader |
| MU | +4.2% | Leader |
| CRWV | -8.6% | Laggard |
| LRCX | -3.4% | Laggard |
| VRT | -3.0% | Laggard |
| AMAT | -2.6% | Laggard |
| SMCI | -2.5% | Laggard |
Sector Read-Through
Semis are splitting. AMD and MU worked while LRCX and AMAT softened — a divergence between compute demand and the equipment that enables it. When leaders and equipment suppliers disconnect, it often reflects shifting expectations about the timing of the next capex cycle rather than its existence.
AI infrastructure fatigue. The CRWV/VRT/SMCI cluster underperforming together is notable. These names had carried the "build-out" trade; a coordinated pullback suggests investors are stress-testing capex absorption, power constraints, and margin durability at the infrastructure layer.
Crypto rails re-engaged. COIN and HOOD's double-digit and mid-single-digit gains signal renewed appetite for exchange volume and retail activity — a distinct factor from AI and worth tracking as an independent risk-on gauge.
The Week Ahead
Market participants may find it instructive to monitor whether the AMD/MU strength broadens back into the semi-cap equipment complex, or whether the LRCX/AMAT softness deepens — the latter would suggest the capex-timing debate is intensifying. The CRWV pullback (-8.6%) is worth watching for signs of stabilization or continuation, as it has been a bellwether for the neocloud sub-theme. In crypto-linked equities, the COIN/HOOD advance places focus on whether follow-through requires sustained digital-asset strength or can persist on trading-volume dynamics alone. As always, treat single-week moves as data points, not trends; confirmation typically requires multi-week persistence and volume corroboration.
Key Takeaways
- Rotation, not risk-off: capital is moving within AI, not away from it.
- Compute over capex: AMD/MU outperforming LRCX/AMAT suggests investors favor end-demand over build-cycle exposure.
- Infrastructure layer under review: CRWV, VRT, and SMCI declining together warrants attention to the neocloud/power thesis.
- Crypto rails independent bid: COIN +10.8% and HOOD +6.4% point to a risk factor operating separately from AI.
- Watch the semi-cap tell: re-coupling of equipment names with compute leaders would confirm capex conviction; continued divergence would not.
Educational only. Not financial advice.